The honest answer is that it depends on the source of the water. A standard homeowners policy usually covers sudden and accidental damage, such as a pipe that bursts, and usually excludes water that rises from the ground, seeps through a foundation or backs up through a drain. Many Waunakee homeowners find out which side they are on only after a loss.
This guide explains the pattern in plain language, using what the Wisconsin Office of the Commissioner of Insurance says about common water losses. It is general information, not advice on your policy. Your insurer decides coverage, and the wording of your own policy controls.
If water is spreading right now, call the 24/7 line first and read the rest afterward.
The basic rule: from above versus from below
The Wisconsin insurance commissioner describes a simple pattern. Water damage that starts from above or inside the house, such as a burst supply line or an overflowing appliance, is generally covered by a standard homeowners policy when it is sudden and accidental. Water that comes from below, including groundwater and seepage through the foundation, generally is not.
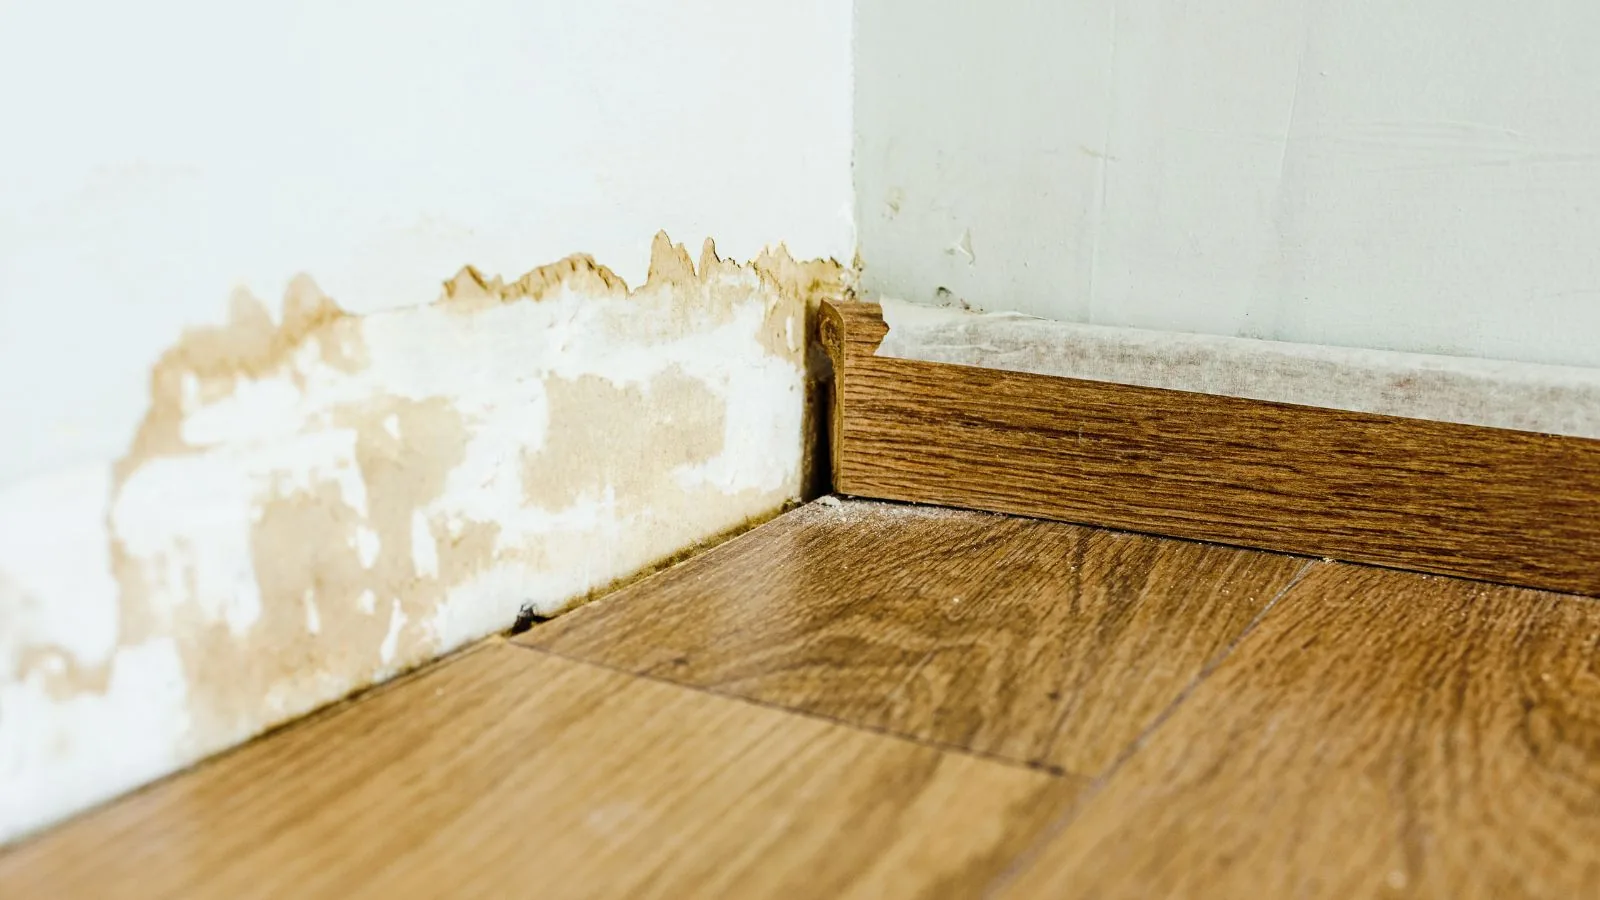
That rule explains most surprises. A split pipe in the wall is often covered. A wet basement after a week of rain usually is not. The same finished basement can be wet either way, so the cause matters more than the damage.
Common water losses and how policies usually treat them
Treat this as a starting point and confirm with your insurer.
| Cause | Often covered? | Notes |
|---|---|---|
| Burst or frozen supply pipe | Usually yes | Sudden and accidental. Neglect can change this. |
| Appliance or water heater failure | Usually yes | The failed part itself is often excluded. |
| Roof leak from storm damage | Usually yes | Wear and long-term leaks often are not. |
| Sewer backup or sump overflow | Usually only with an endorsement | Ask about a water backup rider. |
| Flood or groundwater | Usually no | Needs a separate flood policy. |
| Slow, long-term leak | Often no | Maintenance exclusions are common. |
Not sure what your policy covers?
Call your insurer, then call us for the documentation.
The endorsement most people miss
The commissioner notes that sewer backup and sump pump overflow generally need a special endorsement. It is often cheap compared with the cost of a backed-up basement, and it is the coverage people most often wish they had. Read the declarations page or call your agent and ask a direct question: do I have water backup coverage, and what is the limit?
Limits matter as much as the yes or no. Some endorsements cap the payout at a modest amount, and a finished basement can exceed it quickly. Ask for the number.
Why this matters in Waunakee
Dane County's 2017 hazard mitigation plan lists one structure in Waunakee in the 100-year floodplain and 22 in the 500-year floodplain, with none in the floodway. The mapped exposure is small, which is why flood insurance is easy to overlook. The August 2018 Dane County flooding, with more than $154 million in damage and 1,544 residences affected, shows that heavy rain can reach homes far from any mapped zone.
The Wisconsin insurance commissioner also notes that a National Flood Insurance Program policy generally has a 30-day waiting period. That means a policy bought the day before a storm will not help. If you live near Six Mile Creek or in a low area, look at your parcel on the FEMA Flood Map Service Center before the next wet season.
What to check in your own policy this week
- Whether you have a water backup or sump overflow endorsement, and its limit.
- Whether you hold a separate flood policy and when it started.
- Your deductible for water losses, which may differ from other perils.
- Exclusions for gradual leaks, wear and neglect.
- What the policy says about reasonable steps to protect the property after a loss.
What restoration crews can and cannot do for a claim
A restoration crew cannot decide coverage. What it can do is document the loss: photos, moisture readings, the water category and a written scope of work. That record helps your adjuster see what happened and what it takes to fix. See the burst pipe page and the basement page for how the work runs on the two most common losses.
If the home is in a nearby town, the same applies in Dane, DeForest and Mazomanie. Coverage depends on the policy, not the town.
One more practical step
Keep a copy of your policy declarations page where you can find it quickly, because coverage questions come up on the first call to your insurer.
Insurance and water damage questions
Does homeowners insurance cover a burst pipe?
A sudden and accidental pipe failure is generally covered. Damage from neglect or a long-running leak may not be. Check your policy or ask your insurer.
Is a flooded basement covered?
It depends on the source. A supply line failure may be covered, while groundwater, seepage and flood generally are not.
Do I need a separate flood policy in Waunakee, even outside the floodplain?
Mapped flood exposure in the village is small, but the 2018 county flooding reached many homes. A separate flood policy covers rising water and usually carries a waiting period, so decide before storm season.
Will a restoration company handle my claim for me?
No. We document the loss and explain the scope, and your insurer decides coverage. You deal with your own adjuster.